Written by: Fatima Younes
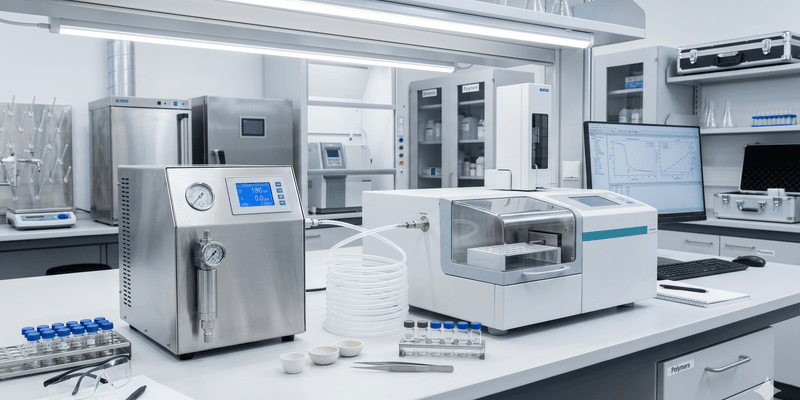
The global laboratory gas generator market is witnessing a significant structural transformation, as industry players shift towards replacing traditional gas cylinders with on-site direct production systems. These shifts are supported by safety requirements, cost predictability, and supply chain flexibility, in addition to increasing analytical needs in the pharmaceutical, biotechnology, and clinical diagnostics sectors.
Demand Drivers and Market Challenges
The primary demand drivers are centered around the increasing density of analytical instruments such as chromatography and spectrometry devices, which require continuous, high-purity supplies of nitrogen, hydrogen, and zero air. Regulatory safety standards also contribute to reducing reliance on high-pressure cylinder storage. Conversely, the most prominent obstacles facing market expansion include high initial capital costs, limited service infrastructure in some emerging markets, and ongoing competition from liquid gas and traditional cylinder suppliers.
Sectoral Structure and Regional Distribution
The pharmaceutical manufacturing and biotechnology sectors account for the largest share of usage due to their intensive reliance on precise analysis and quality control. Meanwhile, the Asia-Pacific region is emerging as the fastest-growing market, supported by the expansion of laboratory infrastructure and increased research spending, while North America and Europe maintain their positions thanks to strict environmental and operational safety standards, leading to projections of stable growth over the coming years until 2035.