Written by: Ahmed Abdel Salam
Venezuela seeks to inject huge investments into the oil and gas sector over the next five years, aiming to enhance its production capabilities and exploit its oil reserves, which are considered the largest in the world. Venezuelan authorities plan to attract about $76 billion in private capital, as part of tireless national efforts to revive the oil industry, which has seen a noticeable decline from its historical peak production.
An ambitious plan to increase production
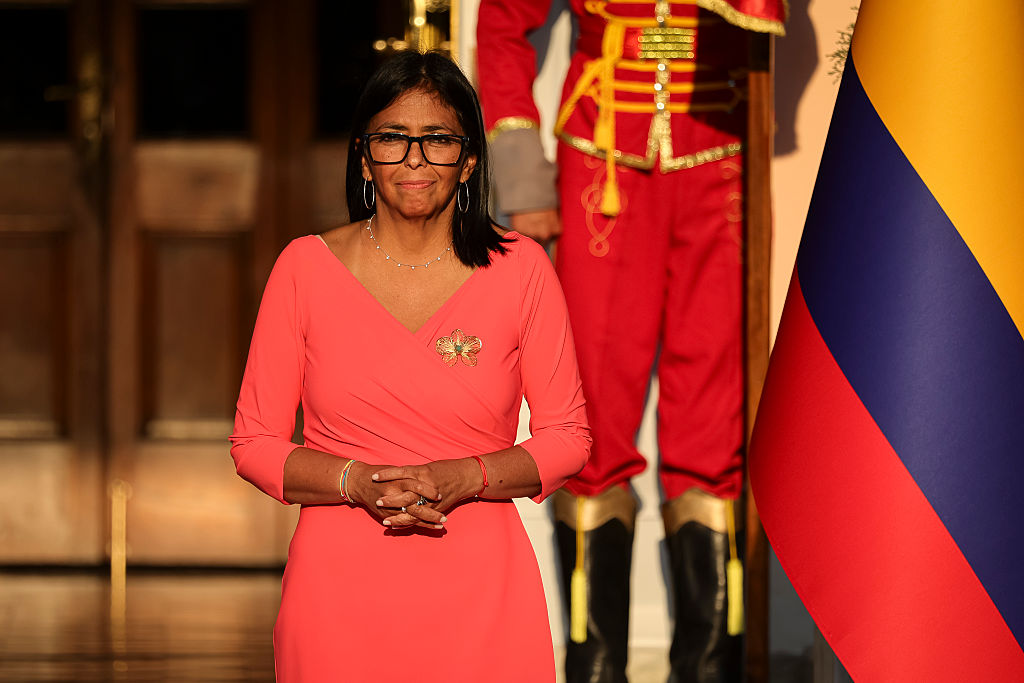
Delcy Rodriguez announced, during an energy conference held in the city of Maracaibo, that the Venezuelan government has signed 61 agreements within a new legal framework that regulates the energy sector, with 44 additional agreements under negotiation. These partnerships aim to integrate foreign capital with local expertise and resources, which could contribute to creating more than 324,000 direct and indirect jobs. These moves aim to stimulate crude oil extraction and develop the liquefied gas sector, such that local production is covered first and then moves towards export.
Challenges and obstacles facing the energy sector
Despite the high ambitions, Venezuela faces serious technical and structural challenges, as the infrastructure suffers from aging extraction equipment and a lack of electricity supply and stability, in addition to the urgent need for trained technical labor. Concerns regarding political stability, the historical precedent of nationalizing assets, and legal uncertainties also pose major obstacles that may affect the decisions of international investors. Observers point out that the sustainability of these investments requires close coordination and continuous reforms to modernize vital facilities in oil fields.
Current efforts are based on international convergences to support the restoration of oil activity, including agreements with global companies such as Chevron, which has expanded its rights in the Orinoco Belt, in addition to major projects aimed at increasing daily production significantly by 2028. However, the effectiveness of these plans remains dependent on the state's ability to actually implement projects and overcome the operational bottlenecks that hinder the conversion of financial commitments into actual oil production.