Written by: Islam El-Sakka
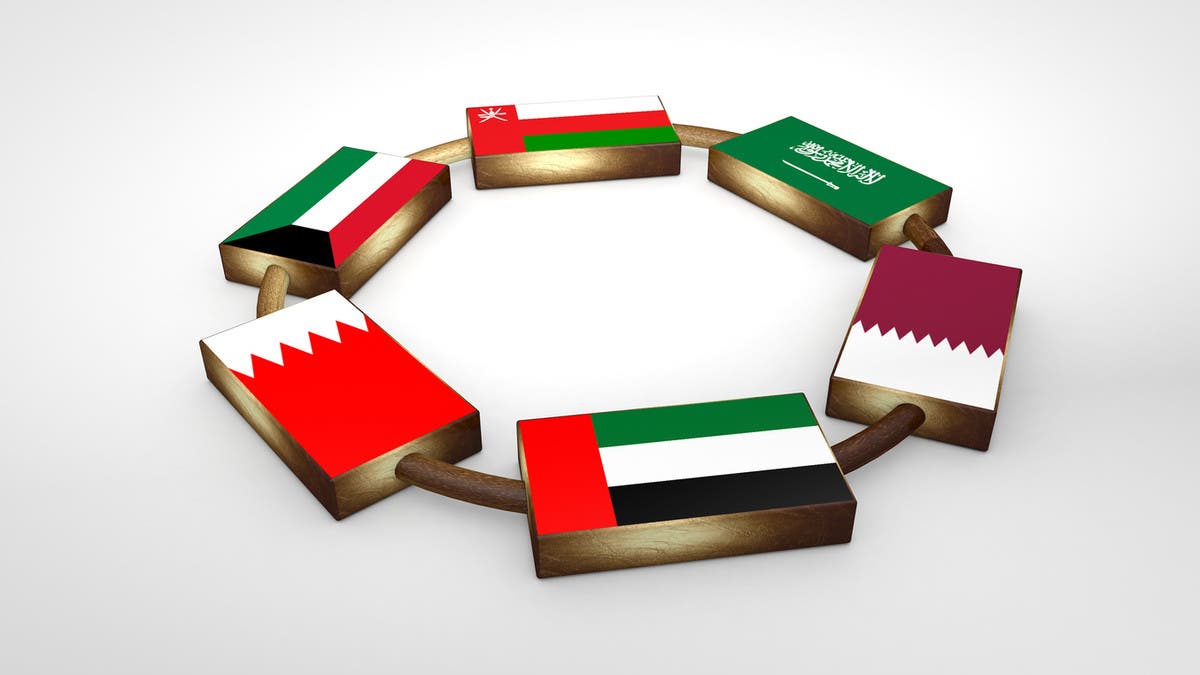
The Gulf Cooperation Council (GCC) countries are facing a delicate phase that requires major economic transformations in light of continuous energy and oil market fluctuations, and the impact of rapid geopolitical changes on vital waterways in the region. This new reality has made re-engineering the national economy from within an urgent necessity that goes beyond traditional, excessive reliance on oil revenues and energy wells.
Sovereign Taxes and Income Diversification Tools
Sovereign taxes, specifically Value Added Tax (VAT), stand at the heart of this economic confrontation as one of the most important strategic lines of defense to secure government budgets and mitigate external shocks. Through these financial and legislative tools, Gulf governments seek to build a flexible, sustainable economy capable of facing future financial challenges independently of oil price fluctuations.
Diversity of Tax Models in the Gulf
Despite the regional trend towards fiscal reform, the tax map in Gulf countries does not take a unified form, as a clear variance appears in the applied models. While some countries have taken bold and advanced steps, raising the tax ceiling, other countries preferred to wait and study the steps carefully to take into account the financial buffers and legislative specificities of their markets.
Balancing Revenue Collection and Economic Support
The most prominent challenge facing decision-makers at the current stage revolves around how to achieve a difficult equation that accurately balances collecting the revenues necessary to finance the general treasury, while maintaining the attractiveness of the business and investment environment, in addition to protecting the purchasing power of citizens. The question remains open as to the extent to which countries that are late in imposing VAT will join the path adopted by neighboring countries.